The Bank That Learned to Build Again
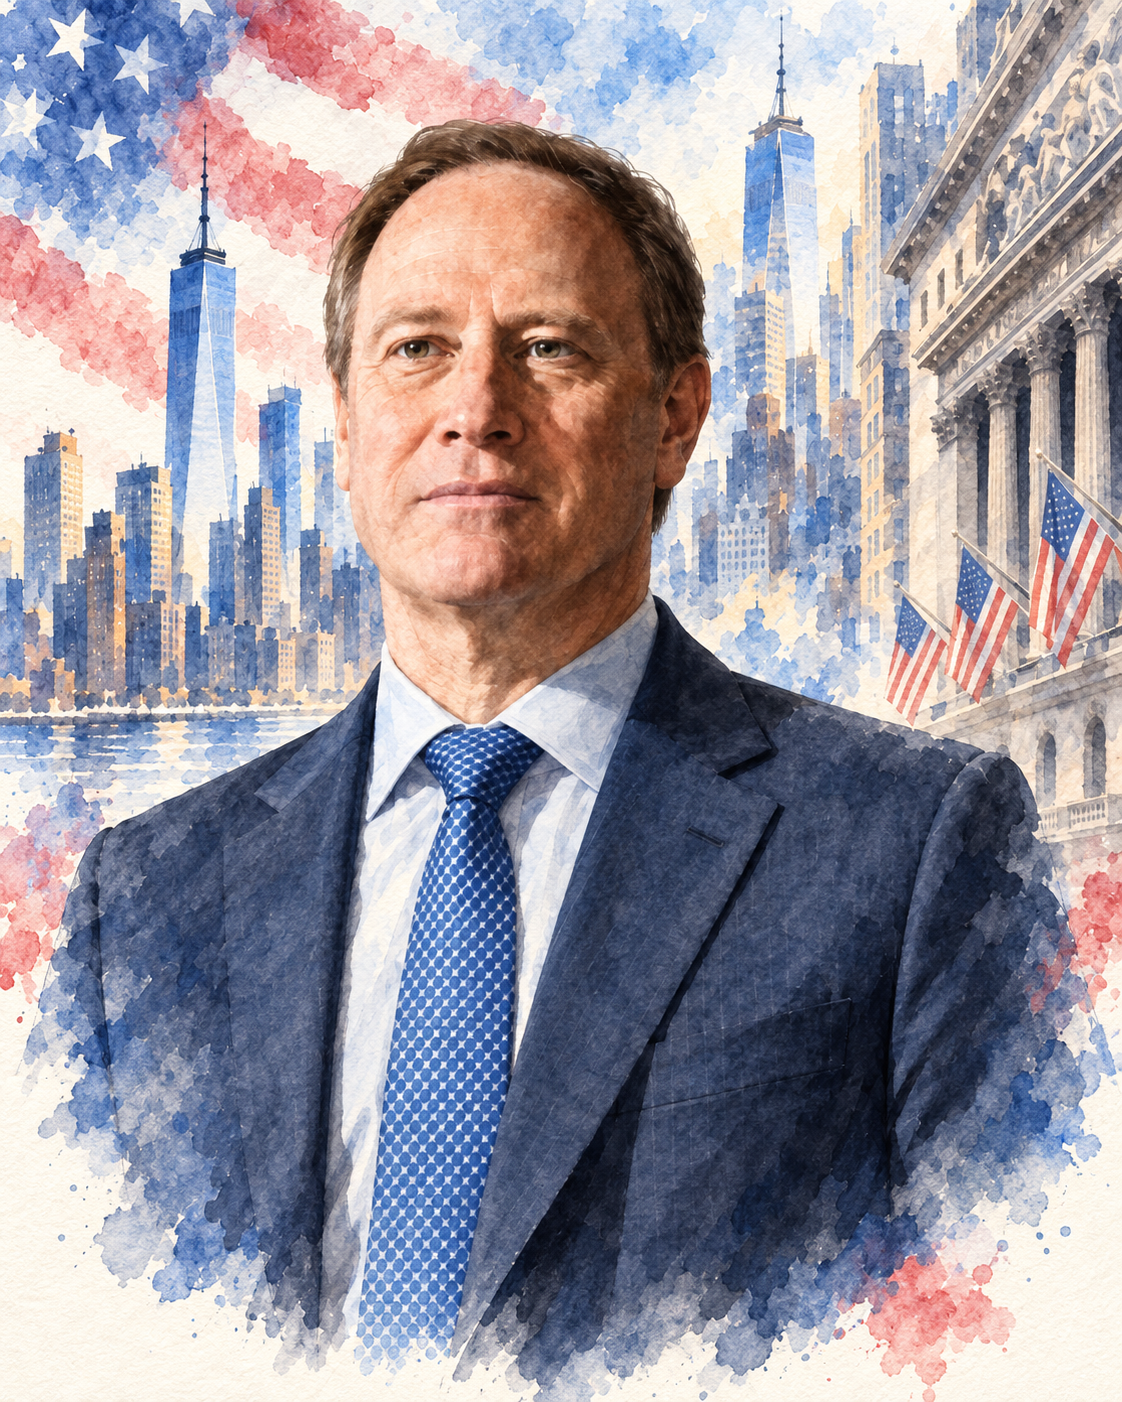
Ted Pick and Morgan Stanley’s move from transactions to infrastructure
For much of the digital era, Wall Street became extraordinarily good at financing businesses that could scale faster than their physical footprint. Software companies did not need power stations, transmission grids or vast industrial complexes and the defining businesses of the age could increase revenues far faster than factories, pipelines or railways could ever be built.
Artificial intelligence is beginning to reverse that logic. The next technological economy is becoming extraordinarily physical, requiring semiconductors, data centres, cooling systems, transmission capacity, power generation and vast quantities of electricity. Morgan Stanley estimates that AI infrastructure investment is moving into the trillions, while hyperscalers are increasingly looking beyond their own cash flows towards debt, structured finance and other forms of external capital.
Morgan Stanley does not need to own the infrastructure to shape which infrastructure becomes financeable.
That changes what an investment bank is being asked to do — and makes Ted Pick an unusually revealing figure through which to watch Wall Street change.
A markets banker
Pick is not a retail banker who happened to arrive at the top of Morgan Stanley. He joined the firm in 1990 and spent much of his career inside the machinery of capital markets, running Institutional Equities, helping rebuild the Fixed Income business and later heading the Institutional Securities Group, with responsibility across investment banking, equities, fixed income, global capital markets and research.
During the financial crisis, he worked in Equity Capital Markets as Morgan Stanley helped clients raise capital under extraordinary conditions. He became CEO in January 2024 and Chairman a year later. That background matters because the challenge now confronting Wall Street is increasingly about capital structure rather than simple capital availability.
As Pick wrote to shareholders this year, Morgan Stanley’s underlying mission remains to:
“raise, manage and allocate capital with excellence.”
Ted Pick, Chairman and CEO, Morgan Stanley
It sounds like conventional banking language. In an economy in which technology increasingly depends on enormous physical systems, however, raising, managing and allocating capital is becoming something much larger.
When technology acquires a balance sheet
For years, the largest American technology companies appeared almost uniquely capable of financing themselves. Their businesses generated enormous amounts of cash, their balance sheets were exceptionally strong and debt was available without fundamentally defining their strategic possibilities. AI is changing the arithmetic.
Morgan Stanley argues that the scale of the build-out means balance sheets matter again. As capital expenditure rises, financing is spreading across investment-grade debt, private credit, structured products, securitisation and other public and private instruments. The bank points to Meta’s $27 billion structured joint venture for a U.S. AI data-centre campus as one example of the increasingly complex financial architecture developing around the sector.
The numbers themselves are moving almost as quickly as the technology. During Morgan Stanley’s second-quarter earnings call, Pick said estimates for 2026 data-centre capital expenditure had risen from roughly $575 billion late last year to around $850 billion. The more important point was not the precise figure, but the uncertainty surrounding it: markets are still discovering how large this investment cycle may become and how it will ultimately be financed.
AI may still live in software, but an increasing share of its balance sheet does not.
That is also where the story moves beyond technology. Chips can be redesigned relatively quickly and new AI models can be released within months, but power generation, substations, transmission infrastructure and data-centre campuses operate on entirely different timelines. The financial system increasingly has to bridge the gap between the speed of technological change and the much slower rhythm of physical construction.
$1.5 trillion
Morgan Stanley made the scale of that ambition unusually explicit in August when it launched its U.S. Innovation Infrastructure Initiative, under which the firm intends to facilitate approximately $1.5 trillion of capital raising, financing, advisory and related investment activity over the next decade.
Its definition of infrastructure is deliberately broad. Artificial intelligence, advanced computing, quantum technologies, semiconductors, cybersecurity, aerospace, defence, pharmaceuticals and critical minerals sit alongside digital infrastructure, energy systems, supply chains and the physical capacity required to support an increasingly compute-intensive economy.
The distinction between investing and facilitating is important. Morgan Stanley is not creating a $1.5 trillion fund that will itself own power stations, data centres or semiconductor fabs. Its role is to raise capital, structure transactions, advise companies, connect investors with projects and combine capabilities across investment banking, wealth management and investment management.
That may be precisely what makes the initiative significant. Morgan Stanley does not need to own the infrastructure to shape which infrastructure becomes financeable. In a capital-intensive economy, the ability to construct a viable capital structure can determine whether a project is built at all.
From IPO to capital stack
For much of Wall Street’s recent history, the archetypal investment-banking transaction was relatively easy to recognise. A company went public, issued bonds, acquired a competitor or raised additional equity; the bank structured the transaction, connected issuer and investor, and collected a fee.
The shortage is not necessarily capital itself. The harder task is intermediating it intelligently.
Infrastructure is more complicated. A large AI campus can bring together a technology company, data-centre developer, utility, landowner, power-purchase agreements, banks, private investors and bondholders, with different layers of financing absorbing different kinds of risk. The central question therefore becomes not simply whether capital is available, but which form of capital should carry which risk, for how long and at what price.
Pick has described essentially the same challenge. Some of the AI build-out can be financed from hyperscalers’ own cash flows, some through new debt or equity and some through more specialised structures designed for investor groups with different time horizons and risk appetites. The shortage, in other words, is not necessarily capital itself. The harder task is intermediating it intelligently and directing it towards the right part of the infrastructure chain.
That begins to look less like conventional underwriting and more like financial architecture.
Big Tech enters the credit system
The consequences are already spreading far beyond Wall Street. Alphabet, Amazon and Microsoft are increasingly issuing bonds outside the United States as their investment programmes expand, while the European Central Bank has estimated that U.S. hyperscalers could require more than $1 trillion in capital expenditure by 2028. Planned investment has simply become too large to assume that internally generated cash will always be sufficient.
Their arrival is beginning to reshape credit markets themselves. U.S. Big Tech companies now account for just under 10% of gross new euro-denominated corporate bond issuance by non-financial companies, according to the ECB, with Amazon and Alphabet becoming the two largest issuers in that market this year.
There is an irony in that development. The companies that helped define the asset-light economy are becoming major participants in global credit markets precisely because the next stage of technology is so asset-heavy. AI may still live in software, but an increasing share of its balance sheet does not.
The electricity constraint
Finance is only part of the constraint. The deeper the AI build-out moves into the physical economy, the more electricity itself becomes a determinant of where capital can productively be deployed.
Morgan Stanley Research expects power constraints to become more visible around 2027 and 2028, citing grid underinvestment and supply-chain limitations. Developers are already exploring combinations of natural gas, batteries, nuclear power, microgrids and dedicated generation as data centres seek reliable supplies that existing grids cannot always provide quickly enough.
That changes the nature of investment risk. A data centre with billions of dollars of computing equipment but insufficient electricity is not merely an infrastructure project awaiting completion; its connection to the power system can determine whether the entire investment becomes economically useful.
Banks therefore need to understand questions that once appeared far removed from Wall Street. They need to know where power can realistically be delivered, who will finance new generation and transmission, how long those assets will take to complete, and which risks belong with the technology company, utility, infrastructure investor or creditor.
The distinction between a financial problem and an industrial problem begins to disappear.
Not every dollar creates productive capacity
None of this means that an enormous infrastructure cycle will automatically produce attractive returns. History offers plenty of examples in which enthusiasm for a transformative technology produced too much capacity, mispriced risk or assets whose economics looked very different once the initial excitement passed.
AI infrastructure is exposed to the same possibility. Demand forecasts can prove too optimistic, technology can change before assets have earned back their cost, and leverage can turn an ambitious project into a financial vulnerability. The sheer availability of capital therefore says little about whether every project deserves to be built.
The distinction between a financial problem and an industrial problem begins to disappear.
This may ultimately be where institutions such as Morgan Stanley matter most. The task is not merely to mobilise capital, but to distinguish between investment that expands productive capacity and investment that exists because markets temporarily assume that almost anything associated with AI deserves financing.
That requires discipline alongside ambition. Pick himself has been cautious about forecasting the ultimate size of the AI investment cycle, describing the build-out as still being “really early”. The uncertainty is fundamental: neither banks nor technology companies yet know precisely how large the physical AI economy will become, or how much infrastructure it can economically support.
The integrated bank
Morgan Stanley enters this transition from an unusual position. Under Pick, it is simultaneously a major investment bank, trading house, wealth manager and asset manager. At the end of the second quarter, Wealth and Investment Management together had reached roughly $10 trillion in client assets, while Institutional Securities generated a record $11 billion in quarterly revenue.
That combination gives greater meaning to the firm’s repeated emphasis on the Integrated Firm. Investment bankers can structure transactions, asset managers can provide capital, wealth management can connect private investors with new asset classes, research can assess the industries behind them, and public and private markets can finance different stages of the same investment cycle.
None of these capabilities is new on its own. What is changing is the scale and physical nature of what they are increasingly being assembled to finance.
The bank that learned to build
Morgan Stanley will not pour concrete, manufacture semiconductors or erect transmission towers. Yet in a capital-intensive economy, that may be too narrow a definition of what it means to build.
Construction begins long before the first shovel enters the ground. Someone has to decide how risk will be divided, which investors can carry it, how revenues will support debt, where equity belongs in the structure and how a project can be made sufficiently legible for capital markets to finance it. Without that architecture, many physical assets never reach the construction phase. That is increasingly where Morgan Stanley sits.
The deeper shift is therefore not simply from IPOs to infrastructure. It is from financing companies towards financing the systems those companies depend upon — from individual transactions to capital structures, and from capital structures to industrial capacity.
For Ted Pick, that may become one of the defining questions of his tenure. Morgan Stanley already knows how to move capital through global markets. The emerging challenge is whether an institution built to move capital can also become one of the architects determining what American capital ultimately builds.
This article is part of The New Architecture of American Capital, an Altair Media series examining how banks, private markets and long-term investors are adapting to an economy that increasingly depends on infrastructure, energy and physical capacity.
The series asks a broader question: how is American finance changing as the next growth cycle becomes more capital-intensive, more physical and more dependent on long-term investment?
Credit
Illustration: Altair Media / OpenAI
Caption
Ted Pick, Chairman and CEO of Morgan Stanley. As AI, energy and infrastructure demand ever larger pools of long-term capital, Morgan Stanley is moving deeper into the financial architecture behind America’s physical economy.
